The stop that made the worst day 13× smaller
“No stop” won 99% of days. It also had the worst drawdown in the test.
Hypothetical backtest. SPX 0DTE 25-wide put credit spread, 1 contract, Jan 2015 – Oct 12 2026 (2,960 trading days). Black-Scholes model prices from daily ^GSPC + ^VIX bars, put IV = VIX × 1.25, $0.65/leg fees, $0.15 slippage on stop exits. Daily bars: any touch of the stop counts as a stop, no gaps, no intraday path. Use for relative comparison only, not expected P&L.
The setup
Each day, sell the 25-wide put spread whose credit is closest to ~$1.075 (target $1.00–1.15; average actual credit $1.15). Hold to expiry unless the stop fires. The stop buys the spread back when its value reaches N× the credit received.
Results ($ per 1 contract)
| Stop | Win% | Avg win | Avg loss | Worst day | Max DD | Total | P&L/DD | Stops (would’ve expired worthless) |
|---|---|---|---|---|---|---|---|---|
| None | 99% | 113 | -1,234 | -2,396 | 4,636 | 293k | 63 | 0 |
| 1.5× credit | 81% | 113 | -75 | -100 | 645 | 228k | 353 | 574 (536) |
| 2× credit | 85% | 113 | -131 | -182 | 1,080 | 228k | 212 | 438 (400) |
| 2.5× credit | 88% | 113 | -188 | -264 | 1,663 | 229k | 138 | 354 (316) |
| 3× credit | 91% | 113 | -246 | -347 | 1,736 | 235k | 135 | 280 (242) |
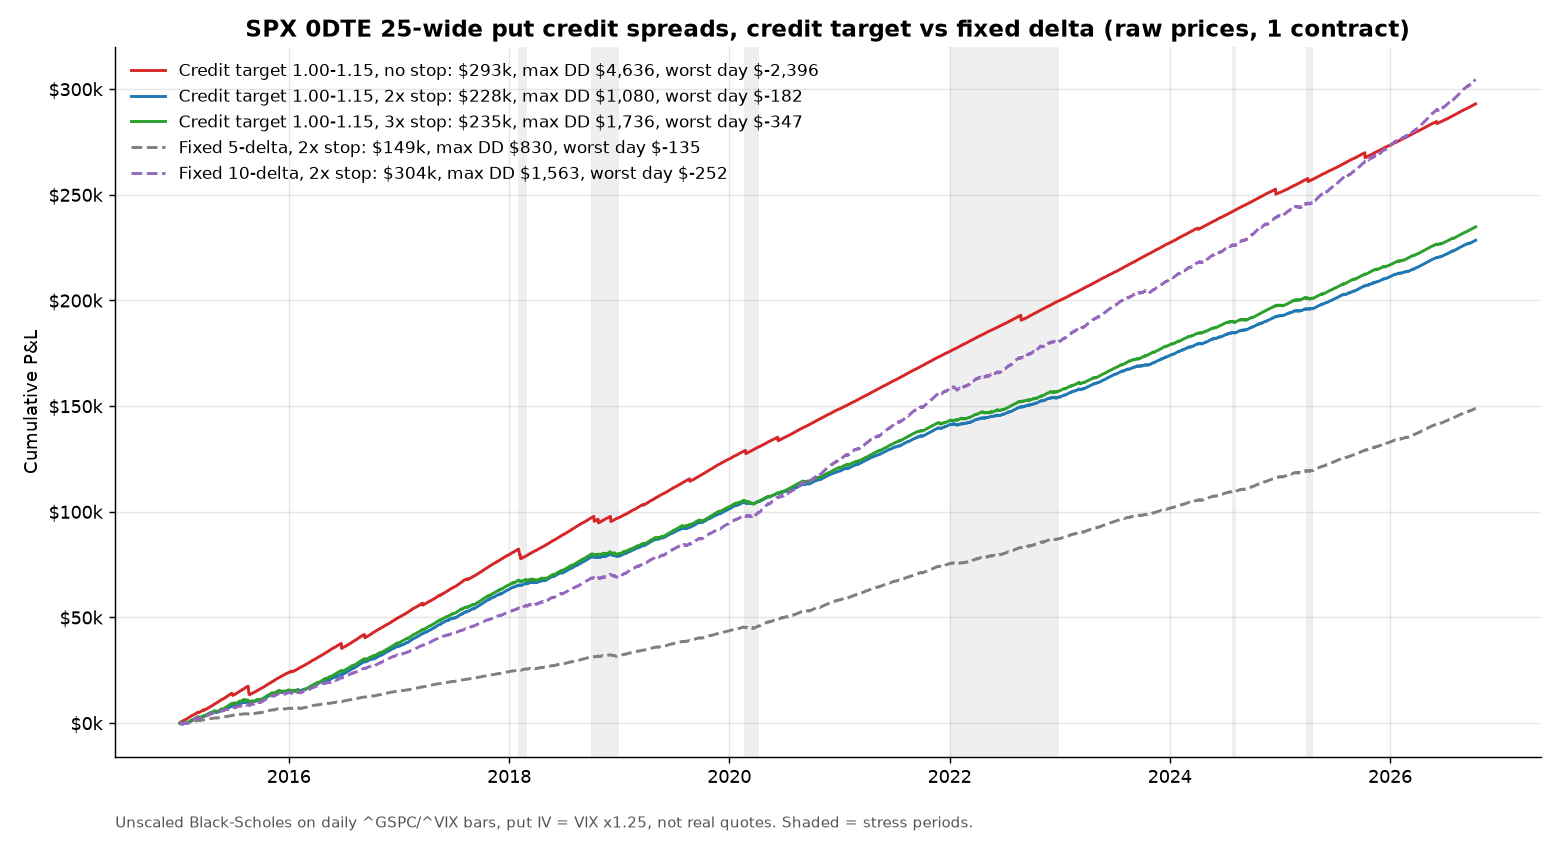
What it shows
- Looser stops raise the win rate, not the risk-adjusted result. Going from 2× to 3× lifts the win rate from 85% to 91%, but the worst day nearly doubles (−182 → −347).
- 2× keeps total P&L about the same as 1.5×–2.5× (228k–229k) and cuts max drawdown from 4,636 to 1,080 compared with no stop.
- The cost: 438 stop-outs, 400 of which would have expired worthless. That’s the insurance premium.
- Why not 1.5×? It scores best on paper (P&L/DD 353), but a 1.5× stop sits inside real 0DTE bid/ask noise, so we treat 2× as the practical rule.
Stress periods (2× stop, $)
| Rule | Feb 2018 | Q4 2018 | Mar 2020 | 2022 | Aug 2024 | Apr 2025 |
|---|---|---|---|---|---|---|
| 2× stop | +1,023 | +590 | +117 | +13,208 | +206 | +78 |
With no stop, Feb 2018 alone was −$2,631.
Caveats
Model prices, not real quotes. Daily bars can’t show gaps through a stop. VIX usually exceeds realized volatility, which flatters the no-stop line. A real 5-delta 25-wide spread often pays well under $1.00.
Get one study a week
Plain-English backtests. No signals, no hype. Free rule card when you join.
Opens our Beehiiv signup page to confirm. Or subscribe free on Beehiiv. Unsubscribe anytime.